Fort Bragg Area Buyer Guide
Want the Benefits of New Construction, But More for Your Money?
Compare newer resale homes near Fort Bragg built in 2020 or later, with 4+ bedrooms, 2,000+ square feet, and asking prices of $350,000 or less.
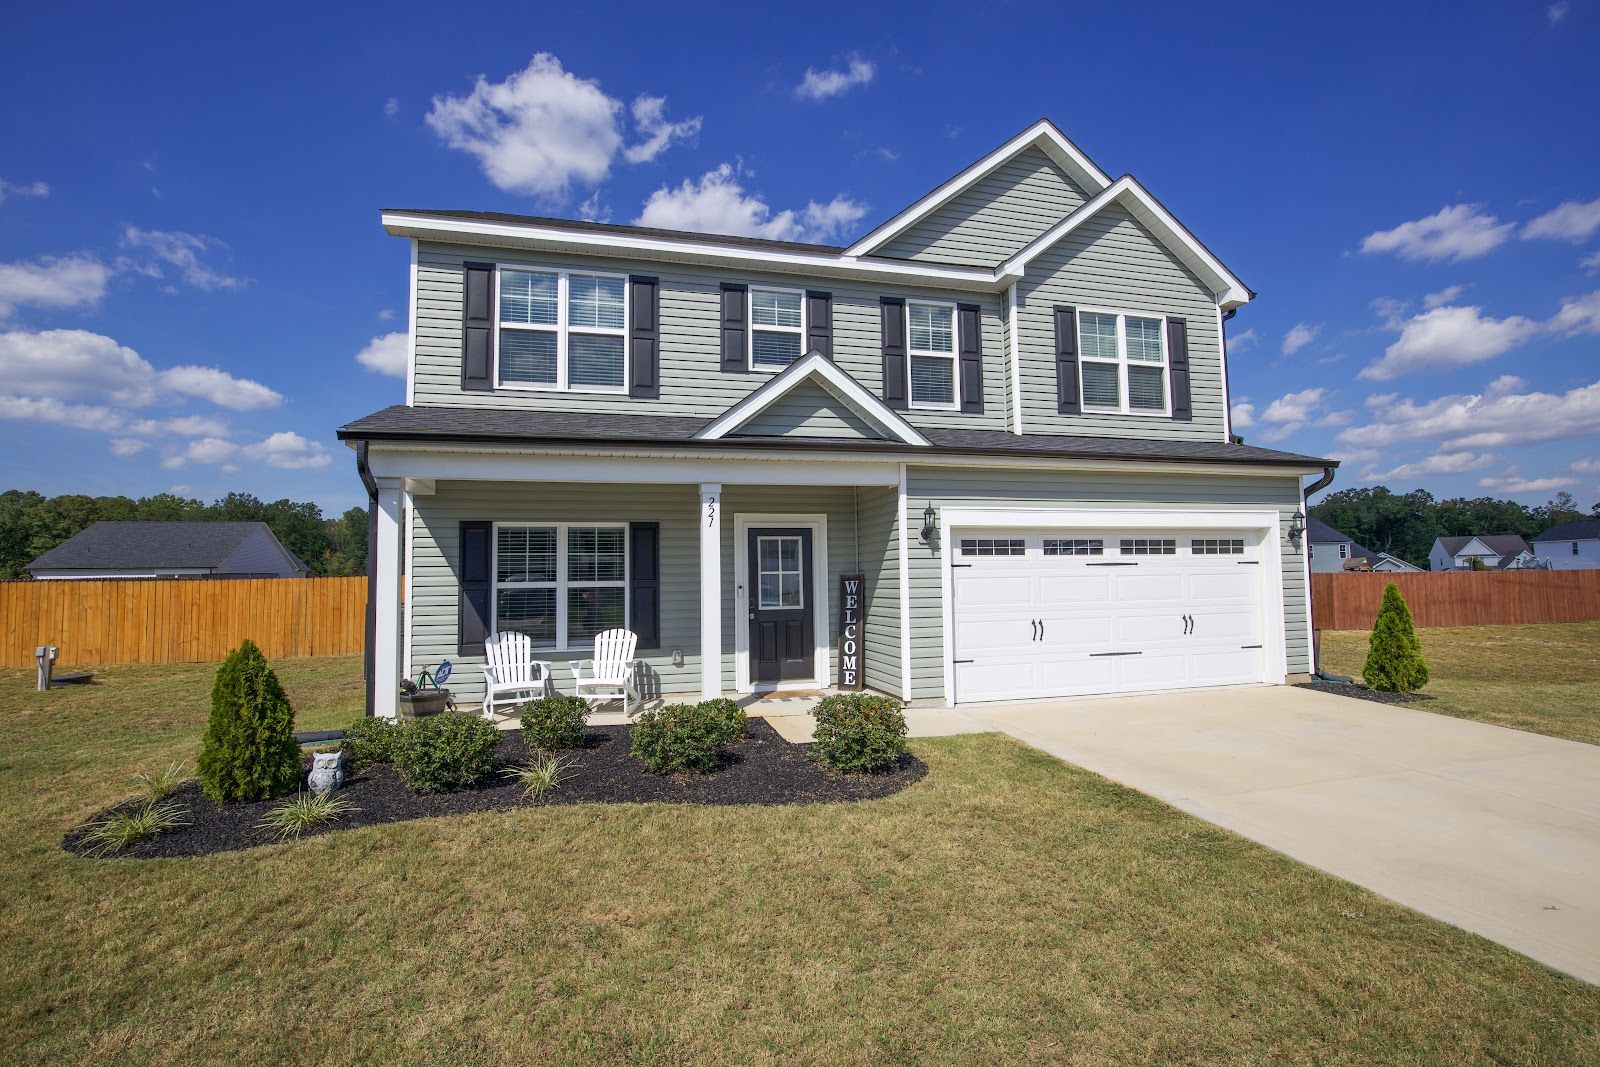
Pictured: 221 Vega Lane in Linden, listed by FTM Realty. See what's already included
We found 20 resale homes built 2020 or newer with 4+ bedrooms, 2,000+ square feet, and asking prices at or below $350,000 across the broader Fort Bragg market. New construction isn't a bad choice. But you may be able to get many of the same benefits of a newer home, plus improvements a previous owner already put in. Here's how to compare what you're actually getting for the money.
Our October 7, 2026 search identified 20 unique newer resale homes meeting these criteria across Cumberland, Harnett, Hoke and Moore counties, including two that were already under contract at the time of the snapshot. The live list further down updates on its own and leaves out homes the MLS marks as new construction.
Do you need new construction to get a newer 4-bedroom home under $350K near Fort Bragg?
No. Brand-new construction isn't the only way to get a 4-bedroom home built in the last few years for $350,000 or less near Fort Bragg. There's a second group of homes: newer resales, built 2020 or later, that someone has already lived in.
It's a small group. In the same search, new construction outnumbered resale by more than three to one. Half of the newer resales were in Cumberland County, so it helps to know where to look and what to compare.
What's for sale right now
Resale homes with 4+ bedrooms, at least 2,000 square feet, built 2020 or later, and listed at $350,000 or less in Cumberland, Harnett, Hoke and Moore counties. Search date: October 7, 2026.
20Unique resale homes that fit (2 under contract)
$342KTypical asking price (median, about $342,000)
2,220Typical square feet (median, about)
2022Typical year built (median)
8Built 2023 or later
7Asking under $325,000
How we counted: we searched the active listings shown on FTMRealty.com, removed homes that appear twice because they're listed in two MLS systems, and left out homes the MLS marks as new construction. Numbers change daily.
Do you really need new construction?
New construction has real advantages, and for some buyers it's the right call. A newer resale offers a different kind of value. Neither one is automatically the better deal. Compare the whole package, not just the purchase price.
A new home may come with
- Builder incentives, such as help with closing costs or a temporary rate buydown, often tied to the builder's preferred lender
- A builder warranty, with terms that vary by builder
- Brand-new roof, heating and air, water heater and appliances that are installed
- A chance to pick finishes, if you buy early enough in the build
- A predictable move-in date on homes that are already finished
A newer resale may already have
- A fence
- A refrigerator, washer and dryer that stay with the house
- Blinds or other window treatments
- Garage shelving or overhead storage
- Landscaping that has had a few seasons to fill in
- A patio, deck or other outdoor improvement
- A neighborhood where construction is mostly finished
An example from our own listings
A real example: 221 Vega Lane
FTM Realty is the listing brokerage for 221 Vega Lane.
Here's what the whole-package idea looks like in an actual home. 221 Vega Lane in Linden was built in 2024 and is listed at $349,800. It has 4 bedrooms, 2.5 baths and about 2,164 heated square feet on roughly 0.46 acre, plus a front flex room that works well as an office and a two-car garage.
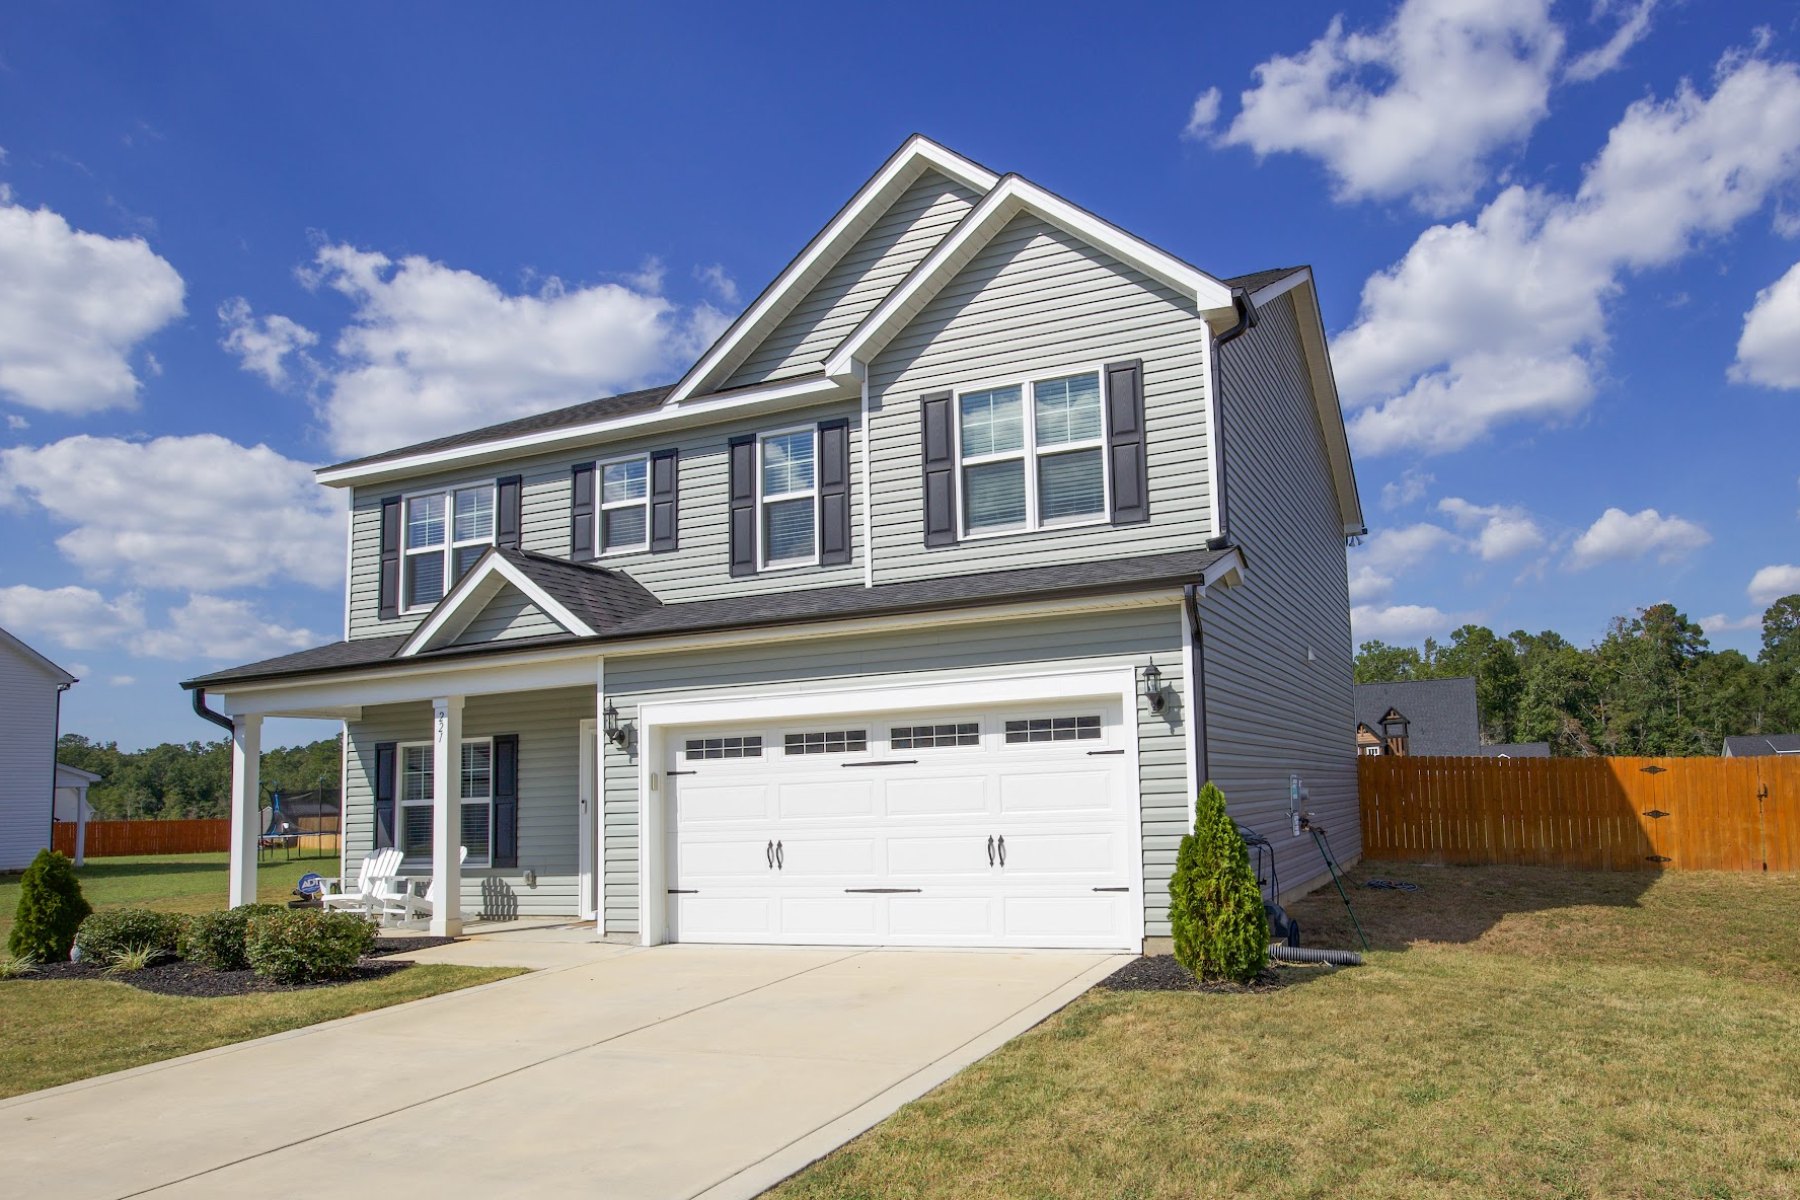
221 Vega Lane, LindenBuilt 2024 • 4 Bed • 2.5 Bath • About 2,164 Sq Ft
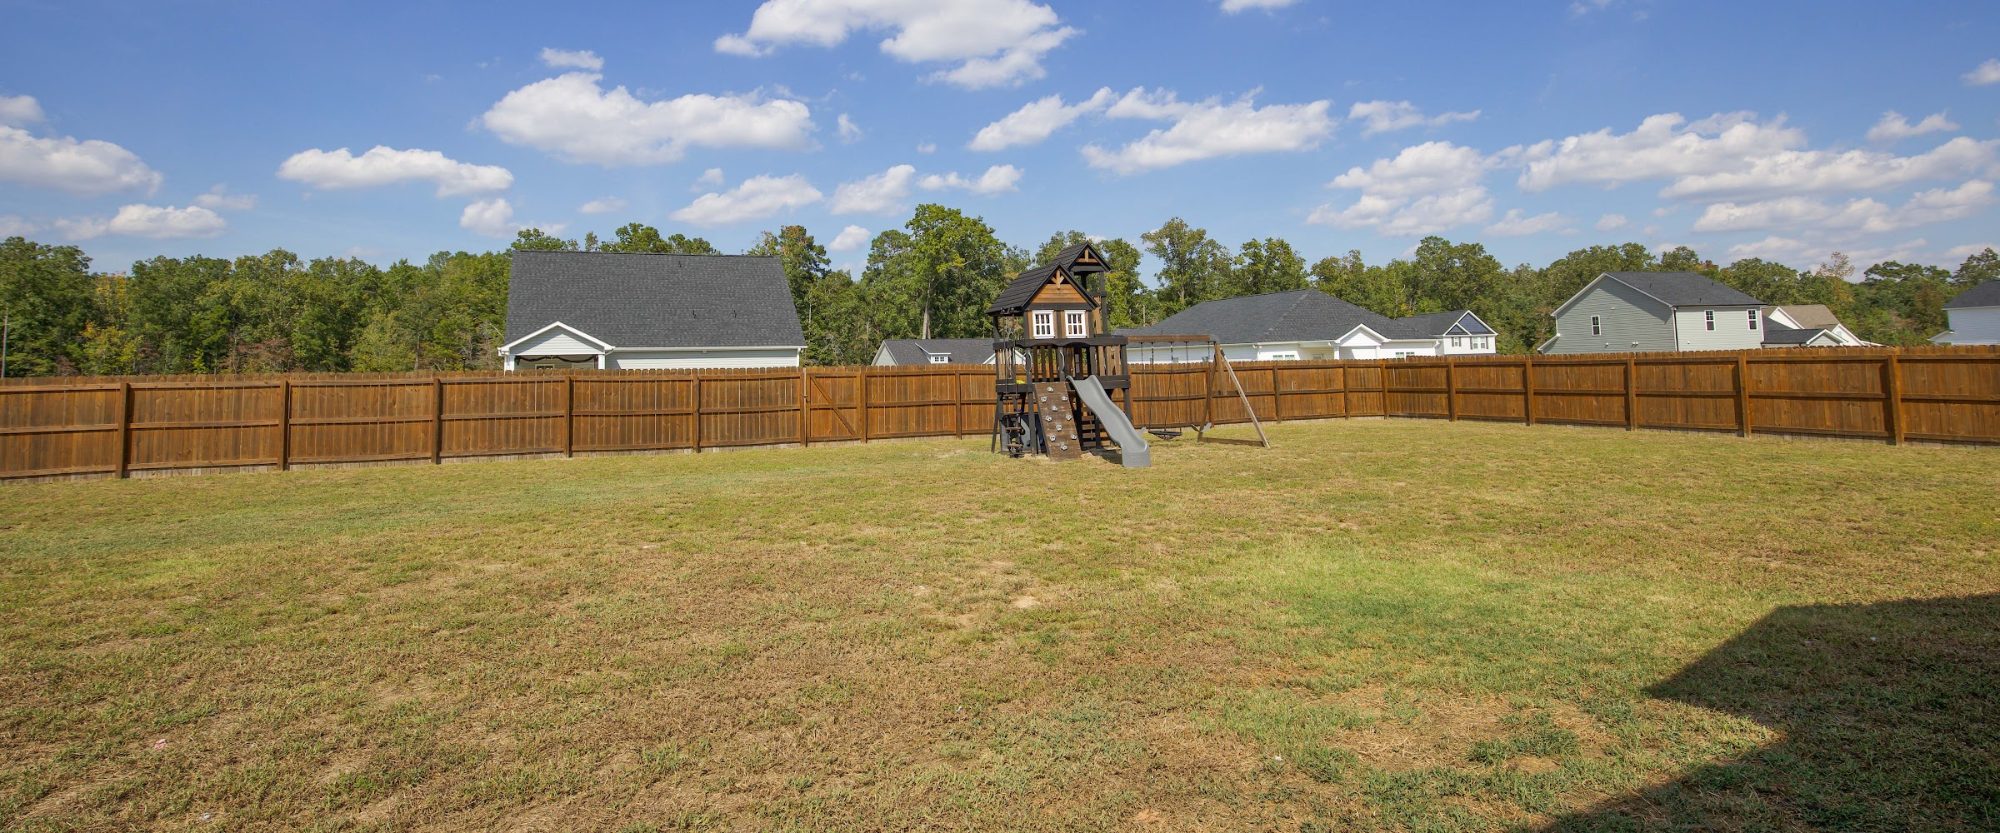
Fenced BackyardPrivacy Fence • Playset Conveys
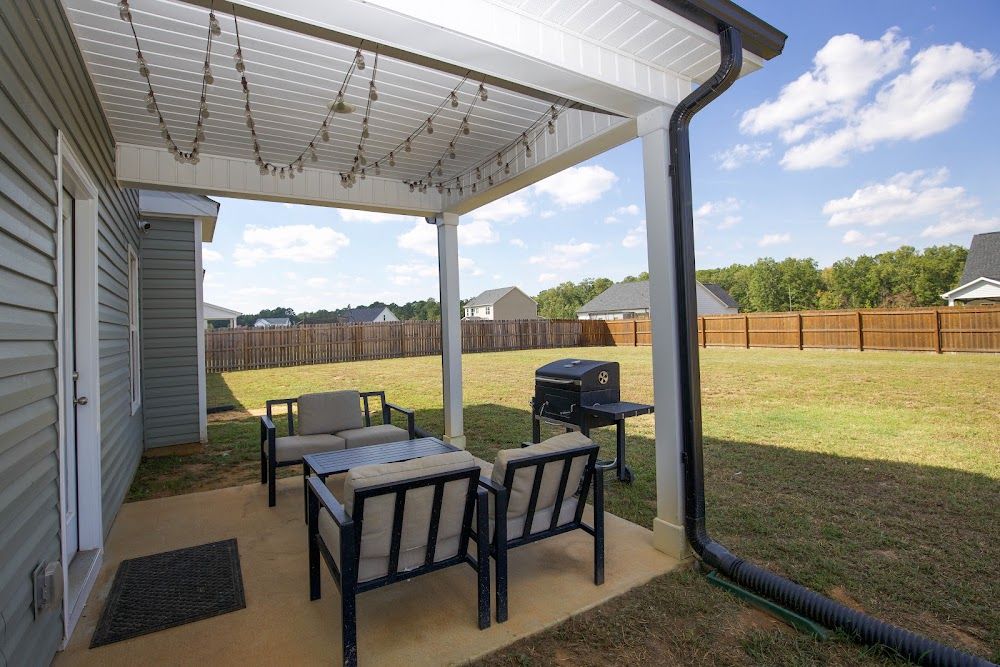
Outdoor SpaceCovered Rear Patio
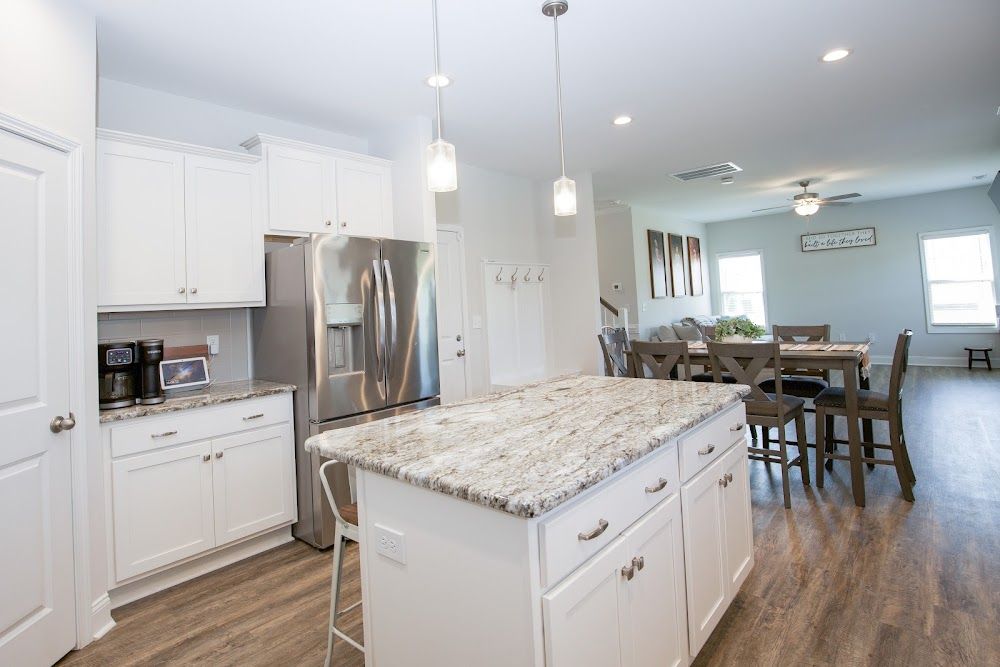
KitchenIsland • Open to Dining
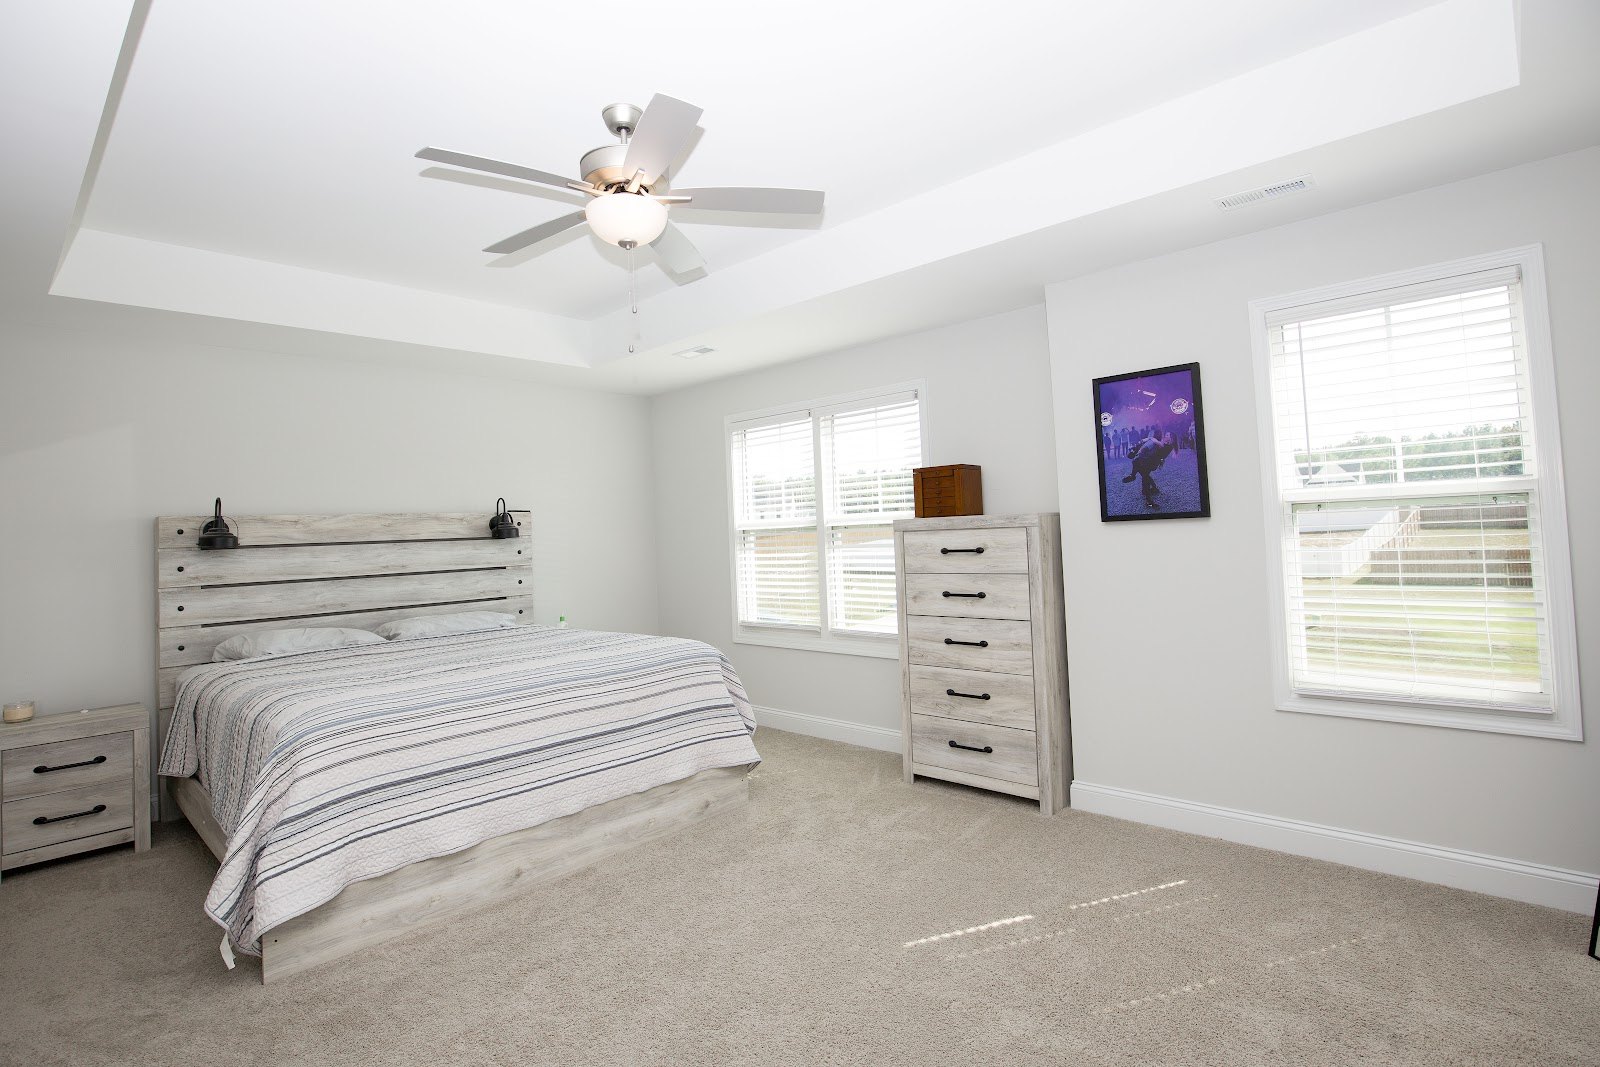
Primary BedroomTray Ceiling • Walk-In Closet
Several things buyers often end up buying after closing are already here:
- A fenced backyard
- A covered rear patio
- Built-in overhead storage in the garage
- Playground equipment, which conveys
- A refrigerator, washer and dryer, which convey
HOA dues are $375 a year. There are no town taxes on this home; county taxes still apply. On the route we've driven, it's about 20 minutes to the Manchester Road gate (Gate 18) at Fort Bragg, depending on traffic. That gate is open weekdays from 5 a.m. to 9 p.m. and closed on weekends and federal holidays, and drive times to other gates or places on post will be different.
Where the newer resale homes are
Cumberland County had half of them: 10 of the 20. Harnett and Hoke had 4 each, and Moore County had 2. Here's what that looks like on the ground.
Linden
Only two homes fit, both built in 2024 on lots of about half an acre in the same neighborhood, Collier Gate Estates. Linden is a small market, so there may be none, one or two homes like this at any given time.
Taxes and HOA. Linden is an incorporated town, but both homes sit outside town limits. Their 2026 Cumberland County tax bills show county, fire district and recreation taxes and no town taxes. HOA dues at 221 Vega are $375 for the whole year, about $31 a month.
Getting to Fort Bragg. The usual routes are US 401 south to I-295, or NC 210 through the Spring Lake area. From 221 Vega, the drive we've taken to the Manchester Road gate (Gate 18) is about 20 minutes, depending on route and traffic. Gate 18 isn't open around the clock, so check current hours on the official Fort Bragg gate page before you plan a commute.
Heading toward Raleigh. US 401 runs north through Lillington and Fuquay-Varina, or you can head east to I-95 and connect to I-40. Plan on about an hour to downtown Raleigh, depending on traffic.
Fayetteville, Hope Mills and Stedman
Seven of the 20 were here. Keep in mind that a Fayetteville mailing address covers a lot of ground, including areas outside city limits. That changes the tax bill, so ask before you run numbers.
Hope Mills
Three newer resales, all built in 2023 or 2024, and no new construction in this price and size range at the time of our search.
Raeford
Four newer resales sat alongside about 21 new builds in the same range. If you're shopping Raeford, you'll likely be comparing builder incentives on one side with what a resale already includes on the other.
Spring Lake
Two resales and about 10 new builds. Spring Lake addresses fall in both Cumberland and Harnett counties, which affects property taxes and school assignment.
Lillington and Cameron
Lillington had two resales and about 16 new builds. Cameron had none in this range on the day we looked.
Moore County
Two homes, one in Vass and one in Carthage, both priced right at the $350,000 ceiling. In our search, these were the only two in Moore County.
A word on drive times
We don't publish blanket drive times, because they depend on which gate you use and when. Gate 18 on Manchester Road, for example, is open 5 a.m. to 9 p.m. on weekdays and closed on weekends and federal holidays (Fort Bragg gate information, updated July 27, 2026). Tell us where you report and we'll map the real route.
New construction vs. newer resale: what to compare
Price
- New construction
- Base price plus options or lot premiums. Builders may adjust incentives instead of price.
- Newer resale
- Set by the seller and the market; negotiable.
- Ask
- What's the contract price after all incentives?
Incentives
- New construction
- Closing-cost help or rate buydowns, often tied to the builder's lender.
- Newer resale
- Seller concessions, negotiated case by case.
- Ask
- Get both in writing and check your loan's limits.
Warranty
- New construction
- Builder warranty; terms vary by builder.
- Newer resale
- Some builder or manufacturer coverage may remain.
- Ask
- What transfers, and for how long?
Fence
- New construction
- Often not included.
- Newer resale
- Often added by the owner.
- Ask
- Is it in the listing? What do HOA rules allow?
Appliances
- New construction
- Refrigerator, washer and dryer may not be included.
- Newer resale
- Sometimes stay with the home.
- Ask
- Is it in the listing and in the contract?
Window treatments
- New construction
- May or may not be included.
- Newer resale
- Often already installed.
- Ask
- How many windows need covering?
Landscaping
- New construction
- Basic sod or seed and young plants.
- Newer resale
- More established lawn and beds.
- Ask
- Drainage? Irrigation?
Storage and outdoor space
- New construction
- Garage and patio as built.
- Newer resale
- Owners may have added shelving, racks, covered patios or sheds.
- Ask
- What stays?
Lot
- New construction
- Varies widely.
- Newer resale
- Set.
- Ask
- Compare actual acreage and usable yard.
HOA
- New construction
- Most newer neighborhoods have one.
- Newer resale
- Same.
- Ask
- Dues, rules, fence and parking limits.
Property taxes
- New construction
- The first bill may not reflect the finished house, depending on timing.
- Newer resale
- Already assessed.
- Ask
- Inside town limits? Check with the county.
Choices
- New construction
- Possible if you buy early.
- Newer resale
- What you see is what you get.
- Ask
- Which upgrades cost extra?
Neighborhood
- New construction
- Construction nearby for a while.
- Newer resale
- More settled.
- Ask
- How many lots are left?
Inspection
- New construction
- Still recommended.
- Newer resale
- Recommended.
- Ask
- Who's your inspector?
Source for the property tax point: North Carolina values property for tax purposes as of January 1 each year, and changes after that date generally show up on the next year's bill (UNC School of Government, "Property Taxes and New Year's Day").
What buyers may still need to buy after closing
Two homes can carry very different first-year costs even when their prices are close. Before you decide, list what each home still needs:
- Fence
- Refrigerator
- Washer and dryer
- Blinds or curtains
- Landscaping beyond the basics
- Garage storage
- Patio cover, shed or other outdoor space
- Gutters
- HOA dues and any transfer fees
- Moving into a home that's still being finished nearby
A simple example
Home A is brand new at $340,000. Home B is three years old at $349,000. On paper, they're $9,000 apart.
Now add up what Home A still needs that Home B already has. If those items cost more than $9,000, Home B may be the better value. But if the builder is paying $10,000 of your closing costs and Home B's seller isn't offering anything, the math can swing right back the other way.
That's the whole idea of this guide: compare the whole package.
Start your search
Pick a starting point. Each one opens a live list of homes for sale that updates on its own.
Fence information depends on how each listing was entered in the MLS, so some fenced properties may not appear in this search.
Which home is actually the better value?
Use this side-by-side list for any two homes you're considering. Print this page, or send us two homes and we'll go through it with you.
| Item | Home A | Home B |
|---|
| List price | | |
| Price after incentives or concessions | | |
| Financing incentive (describe it) | | |
| Help with closing costs | | |
| Fence | | |
| Refrigerator | | |
| Washer and dryer | | |
| Window treatments | | |
| Landscaping | | |
| Storage | | |
| Patio, deck, shed or other outdoor space | | |
| Lot size | | |
| HOA dues per year | | |
| Estimated yearly property taxes (county, plus town if inside limits) | | |
| Warranty remaining | | |
| Route and drive to your gate | | |
| What you'd still need to buy (estimate) | | |
| Total: price after incentives + what you'd still need to buy | | |
Financing, appraisal and inspection basics
Compare loan offers
The Consumer Financial Protection Bureau suggests requesting "multiple Loan Estimates from different lenders so you can compare." That's the cleanest way to see what a builder's lender incentive is really worth (consumerfinance.gov).
Builder and lender incentives
Ask what the incentive is tied to, how long it lasts, and what happens if you use a different lender. Get it in writing before you compare homes.
What a seller or builder can pay
Each loan type has its own rules on what a seller or builder can pay. For conventional loans, Fannie Mae limits these contributions based on your loan-to-value ratio: 3% above 90%, 6% from 75.01% to 90%, and 9% at 75% or less (Fannie Mae Selling Guide B3-4.1-02). FHA generally allows sellers, builders and other interested parties to contribute up to 6% of the sales price toward closing costs, prepaid items and discount points (HUD FHA Resource Center, citing Handbook 4000.1). VA doesn't limit credits toward normal closing costs, but it limits seller's concessions, such as paying the VA funding fee or paying off a buyer's debts, to 4% of the home's reasonable value (VA.gov). Your lender will confirm how this applies to you.
VA loans and newer homes
VA loans work for both resale and new construction (VA.gov). Either way, the VA appraisal checks the home against VA's minimum property requirements, and VA's own guide points out that "an appraisal is not a home inspection."
Appraisals
A newer home still has to appraise. If the value comes in low, buyers often renegotiate, bring cash, or, with VA, ask for a reconsideration of value.
Inspections and due diligence
Newer doesn't mean inspection-free. VA says a home inspection is "highly recommended for every borrower." On a resale, North Carolina's standard Offer to Purchase and Contract (Form 2-T) gives you a due diligence period to complete inspections and other checks.
This section is general information, not legal, lending, appraisal or tax advice. Talk with your lender, attorney or tax professional about your situation.
Want a second set of eyes?
We're Frank and Tracy Murphy, a veteran-owned brokerage in Vass. If you're weighing a new build against a newer resale, send us both and we'll go through the whole package with you.
Frequently asked questions
How many newer 4-bedroom resale homes under $350K are for sale near Fort Bragg?
On October 7, 2026, we counted 20 in Cumberland, Harnett, Hoke and Moore counties, with two already under contract. The live list below shows today's homes.
Is new construction cheaper than a newer resale?
Sometimes. It depends on builder incentives, what each home includes, and what you'd need to buy after closing. Compare the totals, not just the prices.
What doesn't new construction usually include?
It depends on the builder. Items buyers often ask about are fencing, a refrigerator, a washer and dryer, blinds and landscaping beyond the basics. Ask for the builder's list of included features in writing.
Can I use a VA loan on a newer resale or a new build?
Yes, VA loans can be used for both (VA.gov). The VA appraisal applies either way. Your lender will walk you through the details.
Do I still need an inspection on a home that's only a few years old?
We'd recommend it, and so does VA. A newer home can still have issues, and an inspection may catch items to raise before any warranty runs out.
What's the difference between builder incentives and seller concessions?
Builder incentives usually come from the builder, often through its preferred lender. Seller concessions are negotiated with the owner of a resale. Both are subject to your loan program's rules, which differ by loan type.
Where are most newer resale homes in this price range?
In our October 2026 search, Cumberland County had 10 of the 20, mostly around Fayetteville, Hope Mills and Linden.
How far are these homes from Fort Bragg?
It depends on the gate you'll use and the time of day, and some gates aren't open around the clock. Tell us where you report and we'll map your route.
Market snapshot based on active listings from Hive MLS (formerly North Carolina Regional MLS) and the Longleaf Pine REALTORS® MLS, as displayed on FTMRealty.com on October 7, 2026. FTM Realty removed listings that appear in both MLSs and excluded homes the MLS marks as new construction. Counts and medians were calculated by FTM Realty. Information is deemed reliable but not guaranteed.
221 Vega Lane is listed by FTM Realty (Frank & Tracy Murphy, LLC). All other homes shown are courtesy of their listing brokerages.
This guide is general information, not legal, lending, appraisal or tax advice. Equal Housing Opportunity. Last updated October 2026.
Sources: Fannie Mae Selling Guide B3-4.1-02; VA.gov, Funding fee and closing costs; VA.gov purchase loans; VA Home Loan Guaranty Buyer's Guide; HUD FHA Resource Center (Handbook 4000.1); Consumer Financial Protection Bureau, Loan Estimate; UNC School of Government, Property Taxes and New Year's Day; Fort Bragg Garrison gate information; Cumberland County Tax Administration, 2026 tax rates and tax bills.
The live list below updates automatically. A home may appear twice when it's listed in two MLS systems.